A tanker delayed at a narrow shipping passage can now redraw capital budgets thousands of miles away. When crude supplies tighten sharply, the immediate story is familiar: fuel prices jump, inflation returns and consumers feel poorer. Yet behind that pain, another process begins. Scarcity turns energy security from a policy slogan into a purchase order, pushing companies and governments to spend on wells, storage tanks, ports, power grids and technologies that reduce oil use.
That is how an oil-supply crisis could become the unlikely ignition point for an investment boom. A sustained price shock raises the value of every additional barrel that can reach the market, but it also raises the value of every machine, railway and battery that makes a barrel unnecessary. The result would be a race between expanding supply and escaping dependence on it.
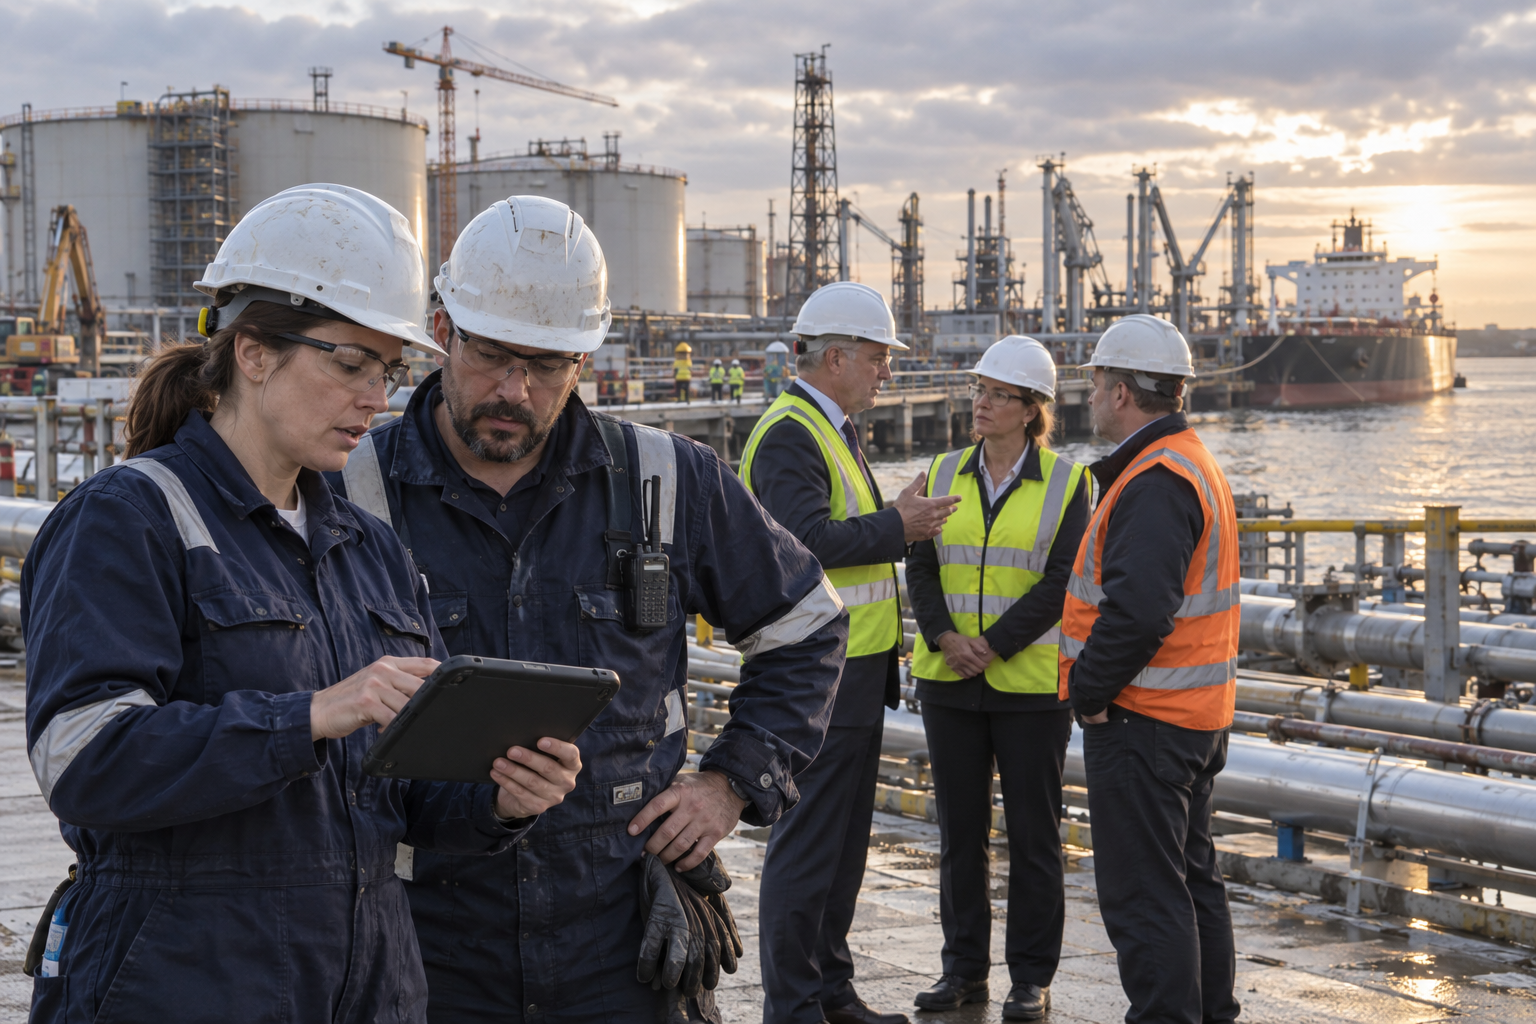
The first wave would be visible in the oil patch. Producers with approved discoveries could accelerate drilling, subsea connections and recovery projects at mature fields. Service companies would order rigs, pumps and steel pipe. Importing nations would enlarge strategic reserves, while trading hubs added tanks and flexible pipelines. Refiners, after years of cautious spending, could revive upgrades that allow plants to handle a wider range of crude grades. Governments might shorten permits for terminals and reinforce ports vulnerable to a single blocked route.
The most valuable projects, however, may sit at the market’s neglected bottlenecks. A new field takes years; a repaired loading berth, extra rail capacity or a digital system that moves cargoes more efficiently can help within months. Investors would begin pricing resilience itself: duplicate power feeds at refineries, alternative shipping links, larger inventories of critical spare parts and insurance-backed contracts with multiple suppliers. These are not glamorous assets, but a crisis makes their cash flows legible.
Then comes the second wave. Airlines would renew fleets faster to cut fuel bills. Freight operators would invest in routing software and more efficient trucks. Cities could speed up electric buses, while households discover that insulation, heat pumps and electric vehicles are not merely climate choices but protection against imported-price shocks. Manufacturers facing expensive diesel and petrochemical feedstocks would redesign processes, recycle more material and bring suppliers closer to factories.
The International Energy Agency already expects global energy investment to reach about $3.4 trillion in 2026. Roughly $2.2 trillion is headed to renewables, nuclear power, grids, storage, low-emissions fuels, efficiency and electrification, compared with about $1.2 trillion for oil, gas and coal. Those figures reveal where a crisis-era boom could become largest: not only at the wellhead, but across an electricity system being asked to replace oil’s mobility and reliability.
Recent history supports that broader reading. Europe’s loss of much of its Russian pipeline gas after 2022 did not produce only a scramble for replacement fuel. It also pulled forward terminals, renewable projects, efficiency programs and new supply relationships. An oil shock could do something similar on a wider geographic scale because transport, food distribution and industry remain tightly connected to petroleum.
Public policy will determine whether the spending becomes productive capacity or an expensive stampede. Emergency stock releases can calm panic, but reserves must later be refilled, creating a predictable source of demand for storage and logistics. Loan guarantees can lower financing costs for grids and strategic infrastructure. Faster approvals can unlock construction, provided environmental and safety standards remain credible. Targeted help for vulnerable households would also preserve political support better than broad fuel subsidies that reward consumption and drain budgets.
There are traps for investors. High prices can collapse demand, invite recession or disappear before a large project is finished. An indiscriminate rush into long-lived oil production could leave costly assets stranded as efficiency and electrification gather speed. Equipment shortages and higher interest rates may inflate construction bills. The likely winners would therefore be projects with short lead times, low operating costs and more than one use: storage that can serve different fuels, ports designed for changing cargoes, and grids capable of absorbing new generation.
The central paradox is that an oil crisis can enrich the industry supplying oil while financing the systems that ultimately weaken its grip. The boom would not arrive as one clean surge. It would spread through drilling towns, shipyards, engineering firms, battery factories and municipal transit depots. Scarcity would impose a heavy economic bill, but it would also expose exactly where the energy system is brittle. Capital tends to move fastest once fragility has a price.